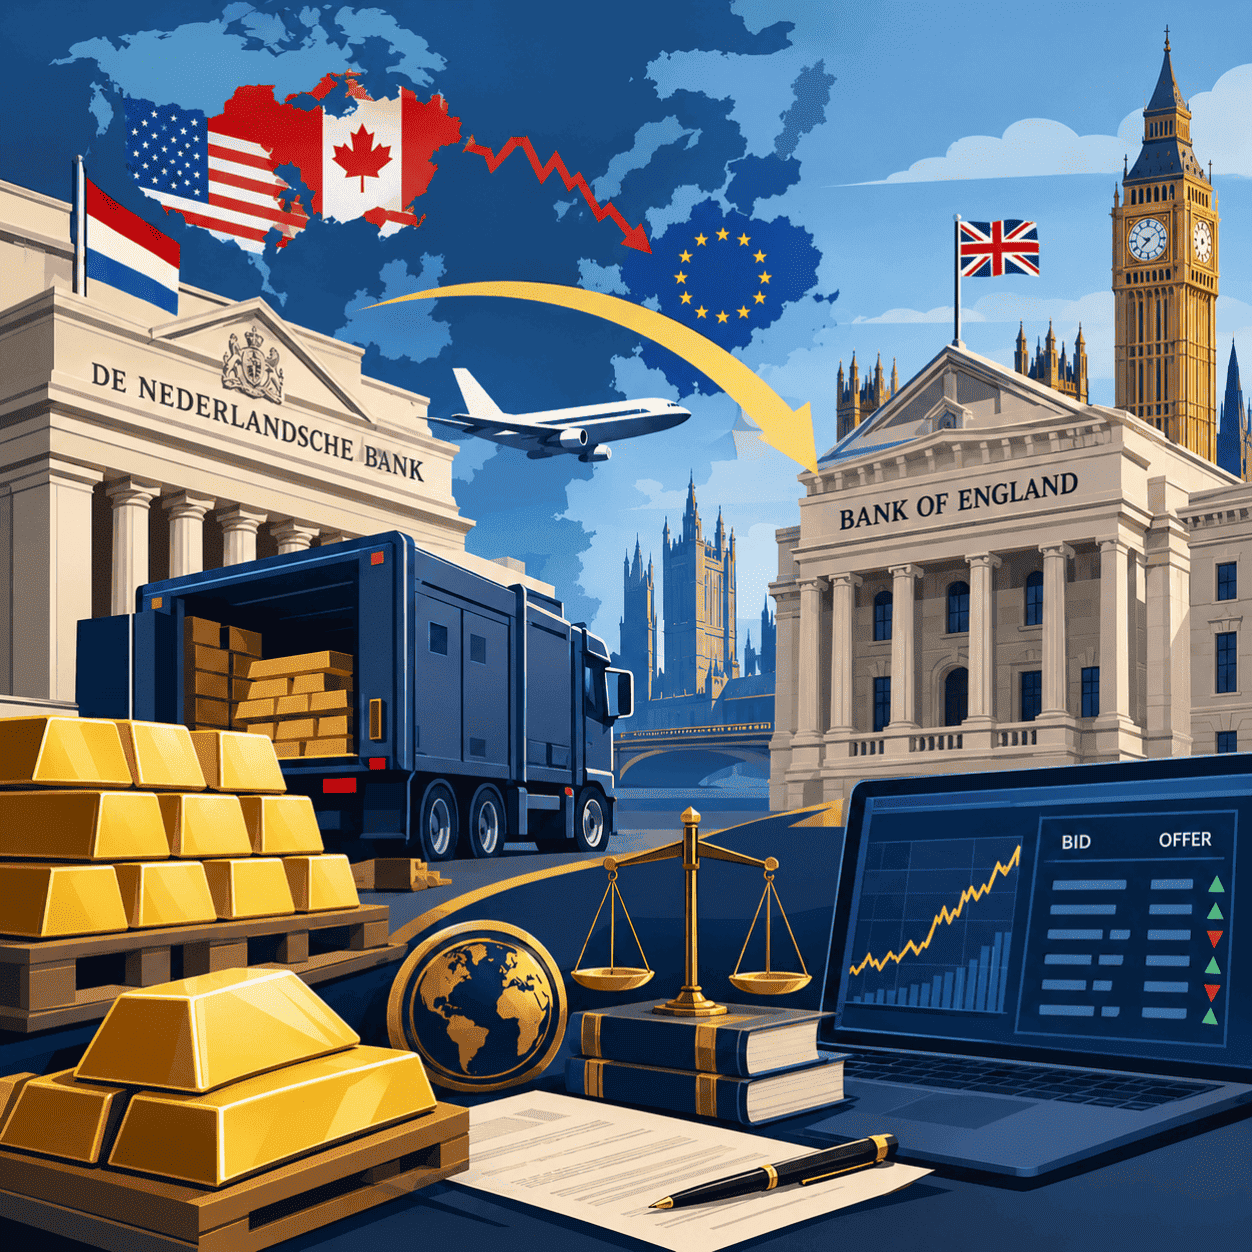
Amsterdam's central bank has just pulled off a manoeuvre that reads like something out of a heist film, minus the balaclavas. On Wednesday the 3rd of September 2026, De Nederlandsche Bank, DNB for short, confirmed it had shifted 86 tonnes of gold worth billions of euros away from North American vaults and into the arms of the Bank of England in London. The operation, quietly assembled over several months between March and August, involved the Federal Reserve's storage facilities in New York and the Bank of Canada's holdings in Ottawa. President Olaf Sleijpen fronted the announcement himself, framing the whole affair as a matter of strengthening resilience and preparedness rather than panic. Twenty-seven tonnes of that gold made an actual physical journey, first to Zeist in the Netherlands, before crossing onward to the British capital. The remaining bulk changed hands through paper rather than pallets, sold in New York and repurchased in London in matching weight and purity. Blimey, one might say, that's a proper logistical juggling act for an institution better known for interest rate memos than transatlantic bullion runs. The timing is no accident, coming hard on the heels of an escalating trade spat between Washington and Ottawa. Who moved it, when it happened, and where the metal now sits are all matters of public record. Why the Dutch felt compelled to act, and how the mechanics actually worked, deserve a proper unpacking.
The backdrop to this manoeuvre is a trade war between two neighbours who used to get along famously. Washington slapped fresh tariffs on Canadian steel, aluminium, timber, and motor vehicles, adding a further 50 percent levy in August on goods worth roughly C$28 billion. Canada, naturally, felt the pinch rather sharply, and the ripple effects unsettled markets far beyond North America. Add to that the still-simmering conflict involving the United States and Iran, a confrontation that has kept global trade routes and investor nerves on edge since the spring. DNB never spelled out precisely what "geopolitical turbulence" meant in its statement, choosing the sort of careful central-banker vagueness that leaves room for interpretation. Sociologically, this reticence is telling in itself, a small institutional echo of a much older human instinct to squirrel away something solid when the world starts wobbling. Nations, much like households during hard times, tend to hoard what they trust, and few things have earned trust quite like gold across centuries of currency collapses, wars, and hyperinflations. The psychology of the herd matters enormously in these moments, since one central bank's decision to relocate reserves rarely stays a private affair, nudging others to reconsider their own arrangements too. Public confidence in monetary institutions rests on visible signals of caution, and shifting bullion to a jurisdiction seen as more liquid sends exactly that sort of signal to citizens, markets, and rival governments alike.
Getting bullion from one continent to another is never as simple as popping it in the post, and the legal architecture underneath this transfer is worth dwelling on. Central bank gold reserves are typically held under custodial arrangements resembling a bailment, a legal relationship in which possession sits with one party while ownership remains firmly with another. Every such arrangement rests on the ancient contractual promise of pacta sunt servanda, agreements must be honoured, a doctrine so foundational that even sovereign states cannot casually wriggle out of it. The doctrine of nemo dat quod non habet, no one gives what they do not have, quietly underwrites the entire swap mechanism DNB used, since only a party holding clear title to specific bars could sell them in New York and arrange for equivalent purity and weight to be handed over in London. This sale-and-repurchase trick spared everyone the trouble of physically melting anything down, relying instead on the fungibility gold enjoys within recognised bullion markets. Custodial contracts between central banks typically include force majeure clauses, allowing either side to suspend performance when extraordinary events, tariffs and armed conflict very much included, make normal operations unreasonable. The related doctrine of rebus sic stantibus, things thus standing, gives states a recognised basis for renegotiating long-term arrangements once circumstances shift dramatically from what was originally contemplated. None of DNB's manoeuvring strayed beyond its statutory mandate either, since reserve management sits squarely within its remit, sparing it any awkward brush with the doctrine of ultra vires, acting beyond one's legal powers. Regulatory frameworks such as the Dutch Bankwet 1998 and the broader Eurosystem governance rules exist precisely to keep this sort of manoeuvre within a lawful corridor amid politics that increasingly resembles the Wild West.
Economically speaking, gold has never entirely lost its shine, its status peculiar because it produces no yield, pays no dividend, and simply sits there looking pretty in a vault. Since the Bretton Woods system collapsed in 1971 and currencies floated free of any fixed gold peg, plenty of economists predicted the metal would fade into a museum curiosity. Reality had other plans, and central banks worldwide have spent the last two decades quietly rebuilding gold allocations as a hedge against currency debasement, inflation shocks, and the sort of political brinkmanship currently playing out between Washington and its trading partners. Holding a chunk of national wealth in an asset immune to any single government's printing press or sanctions regime offers a form of insurance that no fiat currency can fully replicate, no matter how sturdy it appears. The Netherlands' own reserve stood at 612.4 tonnes at the close of 2025, valued around €72.2 billion, a stash substantial enough to matter geopolitically whilst modest enough to relocate without tipping global markets into a tizzy. Opportunity cost remains the standard objection raised against gold hoarding, since that capital could theoretically chase higher returns in equities or bonds instead of sitting inert. Central banks accept that trade-off willingly, treating gold less as a growth instrument and more as monetary bedrock, a last line of defence should confidence in paper assets ever crumble. Diversification theory backs this instinct thoroughly, given that gold's price movements tend to correlate poorly with stocks and bonds, smoothing out a reserve portfolio's bumps precisely when everything else turns choppy. Small wonder, then, that roughly a third of Dutch reserves now sit in London rather than scattered across North America, a rebalancing act any sensible portfolio manager would recognise instantly.
Every working day, twice over in fact, the price of gold gets hammered out through a mechanism most people never think about whilst eyeing a wedding ring in a shop window. The LBMA Gold Price benchmark gets set at 10:30 and again at 15:00 London time through an electronic auction run by ICE Benchmark Administration on behalf of the London Bullion Market Association. Accredited banks and bullion dealers submit their buy and sell orders into this auction, each round adjusting the reference price incrementally until the volume buyers want matches, within a tight tolerance, the volume sellers wish to offload. This iterative dance continues for several rounds within a single session, the algorithm nudging price up when buyers outweigh sellers and down when the reverse holds true, until equilibrium settles the matter for that fixing. History gave this process a rocky start, since the old-fashioned "London Gold Fixing", conducted by five bullion banks over a telephone call since 1919, got scrapped in 2015 after a manipulation scandal rocked confidence in benchmark-setting across financial markets generally. The switch to an automated, auditable auction restored a measure of legitimacy, replacing a cosy old boys' club with something considerably more transparent and harder to rig. Good Delivery bars, the 400-ounce standard bars of at least 995 fine purity accredited by the LBMA, form the physical backbone against which this benchmark price applies, ensuring buyers everywhere know precisely what quality they are trading. Beyond the twice-daily fixing, gold trades continuously around the clock across Sydney, Tokyo, London, and New York sessions, meaning the spot price genuinely never sleeps outside the official auction windows either. This benchmark ripples outward into everything from jewellery pricing and mining contracts to exchange-traded funds and the very sort of central bank swap arrangement DNB just executed, making it arguably one of the most consequential numbers most citizens have never heard of.
Numbers make all of this rather more vivid, so a spot of back-of-envelope arithmetic seems in order. Dutch reserves totalled 612.4 tonnes worth roughly €72.2 billion at the end of 2025, which works out to approximately €117.9 million per tonne once the sums are done properly. Converting tonnes into the troy ounces traders actually quote requires dividing by 31.1035 grams per ounce, giving roughly 32,151 troy ounces per tonne, and running that implied price per tonne through this conversion yields a benchmark near €3,668 per troy ounce at that snapshot in time. Applying this same implied rate to the 86 tonnes relocated produces a headline figure of roughly €10.14 billion changing hands or changing location across the whole operation. The 27 tonnes that actually made the physical Atlantic crossing, valued the same way, comes to somewhere in the region of €3.18 billion worth of metal riding in secure transport rather than shifting merely on a ledger. None of these figures should be mistaken for a live trading price, since gold moves by the minute and the Dutch reserve valuation reflects a year-end snapshot rather than a real-time quote. A retail investor wanting to run the same sums with today's actual spot price need only fetch the current bid and offer, multiply by the weight in troy ounces, and adjust for whichever currency the calculation should land in. Anyone keen to check live pricing rather than trust a snapshot from months back has several credible ports of call, including the LBMA's own published gold price page at lbma.org.uk, the streaming quotes on kitco.com, the World Gold Council's data hub at goldhub.com, and real-time charting available through investing.com or TradingView. Each of these sources publishes bid and offer spreads updating by the second, giving anyone from a curious student to a professional treasurer the exact raw material needed to replicate this sort of sum with figures fresh off the wire.
Stepping back into the legal weeds, sovereign gold reserves typically enjoy a species of immunity from ordinary creditor claims, a protection rooted in the broader doctrine of state immunity that shields central bank assets from seizure amid litigation abroad. This immunity explains, in part, why physically relocating reserves carries genuine strategic weight beyond simple bookkeeping, since possession within a friendly and legally stable jurisdiction like London strengthens a state's practical control over assets that remain formally its own regardless of geography. The philosopher in the room might reach for Horace's old phrase aurea mediocritas, the golden mean, since the Dutch approach here embodies precisely that kind of measured balance, thirty percent kept at home, roughly a third parked in London, and a smaller remainder spread across North America rather than betting everything on a single vault in a single country. Diversifying physical location mirrors diversifying financial exposure, a principle equally at home in portfolio theory and in ancient wisdom about avoiding extremes. Something almost existential lingers in a state choosing, in a digital age dominated by algorithms and cryptocurrency, to still care so deeply about lumps of yellow metal sitting in a basement. Tempus fugit, wrote Virgil centuries ago, time flies. Gold seems curiously exempt from that particular law of decay, retaining purchasing power across millennia in a manner no currency issued by any single government has ever matched. Modern finance dresses this ancient instinct up in spreadsheets, auctions, and swap agreements. The underlying impulse remains gloriously primal, a tribe wanting something tangible to clutch onto whenever the sky looks like it might fall. Contemplating this makes the whole affair feel less like a dry central banking press release and rather more like a chapter in humanity's very long relationship with scarcity, trust, and the stubborn refusal to fully believe that paper promises alone will always be enough.
For ordinary investors as much as central banks, this whole episode doubles as a timely reminder that gold retains a specific job description within a balanced portfolio. Financial advisers routinely suggest an allocation somewhere between five and fifteen percent of a portfolio dedicated to precious metals, functioning as ballast against the sort of volatility equities and bonds cannot always absorb gracefully. Retail routes into gold range from physical coins and small bars bought through dealers, to gold-backed exchange-traded funds trading on stock exchanges just like any ordinary share, right through to allocated storage accounts offered by specialist providers such as BullionVault or the Perth Mint. Each route carries its own costs, storage fees, insurance considerations, and liquidity profile, meaning the choice depends heavily on how quickly an investor might need to convert holdings back into cash. Sociologically, gold buying tends to spike visibly during periods of political anxiety, a pattern researchers have documented across decades of crisis after crisis, from currency collapses in Latin America to banking panics across Europe. This herd behaviour is neither irrational nor purely emotional, resting instead on a rational recognition that trust in institutions can erode faster than most people expect, and physical assets outside any single government's direct control offer genuine comfort during such episodes. Central banks purchasing gold at record volumes throughout the 2020s, a trend well documented by the World Gold Council, signals precisely this same institutional instinct playing out at sovereign scale rather than around kitchen tables. Small investors watching central banks like DNB shuffle bullion around the globe would do well to treat the move as a genuine signal worth heeding, a quiet nudge from institutions with vastly more information and considerably longer planning horizons than most households possess. Cor, when the professionals start moving their gold, ordinary folk might reasonably wonder whether their own savings deserve a similar spot of diversification too.
Picture the scene inside a Bank of England vault deep beneath Threadneedle Street, stacks of dull yellow bars sitting in climate-controlled silence while algorithms hundreds of miles away decide their price twice a day. That image alone captures something rather profound about modern finance, a system both hyper-digital and stubbornly analogue, trading derivatives at light speed whilst still anchoring ultimate value to a metal humans have prized since the days of Pharaohs. The doctrine of lex mercatoria, the law merchant, reminds us that commercial custom regularly outpaces formal legislation, and nothing illustrates that better than a bullion market whose core practices evolved through centuries of merchant habit long before any modern regulator drafted a single rulebook. DNB's manoeuvre, viewed through this wider lens, reads less like an isolated Dutch policy decision and considerably more like one small movement within an ancient, ongoing choreography between states, markets, and the enduring human hunger for something solid to hold onto. Robert Kraft's tabloid troubles and Ed Sheeran's career woes might dominate today's headlines and social feeds. A quieter story about tonnes of gold crossing an ocean carries implications that will outlast most viral news cycles by decades. Modernist commentators love to declare precious metals obsolete in an age of blockchain and digital currency, a claim that keeps getting refuted by the very central banks issuing those digital currencies in the first place. Every accredited trader submitting a bid or offer into that twice-daily London auction participates, whether consciously or not, in a ritual stretching back to ancient marketplaces where merchants weighed metal on simple scales to settle a fair price. Legally robust, economically sound, sociologically revealing, and philosophically rich all at once, this single transatlantic gold shuffle manages to say more about the state of the world in 2026 than most lengthy policy speeches ever could. Whoever said central banking was boring clearly never watched eighty-six tonnes of gold quietly cross an ocean while half the planet argued about tariffs.